
Reviewed by Hazel Nicolasora, CPA
BIR Opens One-Time Tax Abatement Program for Micro Taxpayers: What You Need to Know
If you’re a micro business owner who’s been carrying old BIR liabilities, delinquent accounts, unresolved assessments, or an inactive registration you never formally closed; the Bureau of Internal Revenue is giving you a defined, affordable path to resolve them.
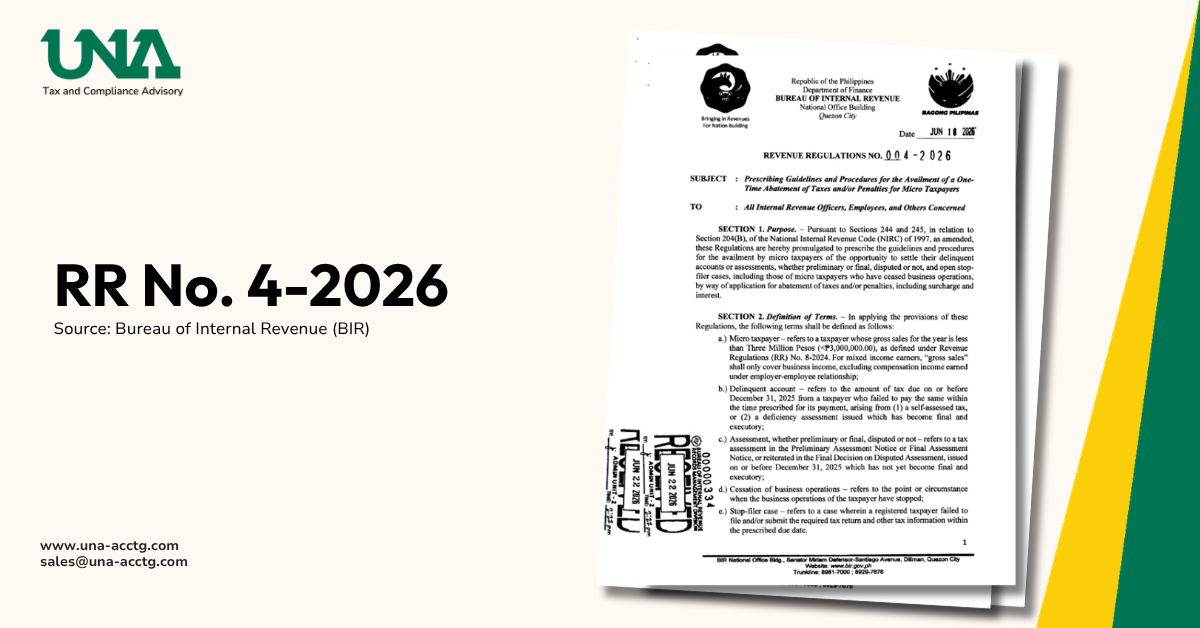
On June 22, 2026, the BIR issued Revenue Regulations No. 4-2026, opening a one-time tax abatement program for qualified micro taxpayers. The program runs until December 31, 2026.
Quick Answer: What is the BIR one-time tax abatement program for micro taxpayers?
The BIR’s one-time abatement program under RR No. 4-2026 allows qualified micro taxpayers to settle delinquent accounts, unresolved assessments, and open stop-filer cases by paying a flat ₱5,000 abatement fee, in place of the full penalties and surcharges that would otherwise apply.
- Who qualifies: Micro taxpayers with annual gross sales of ₱3,000,000 or below
- Liability cap: Covered total basic tax liabilities and/or penalties must not exceed ₱80,000 per taxable year
- Cases covered: Delinquent accounts, preliminary or final assessments (disputed or not), and open stop-filer cases, including businesses that have already ceased operations
- Coverage period: Liabilities existing as of December 31, 2025
- Abatement fee: ₱5,000 per approved application, paid at the Revenue District Office (RDO) with jurisdiction over the taxpayer
- Deadline to apply: December 31, 2026
Who Is This Program For?
The program targets micro taxpayers, those with gross annual sales not exceeding ₱3,000,000 who have unresolved BIR obligations from prior years.
Specifically, it covers three types of cases:
- Delinquent accounts and assessments – whether preliminary or final, and whether currently being disputed or not
- Open stop-filer cases – taxpayers who stopped filing returns at some point but never formally resolved the gap
- Ceased businesses – companies that have already stopped operating but still carry open BIR records
All covered liabilities must pertain to cases that existed as of December 31, 2025. Obligations arising after that date are not covered under this program.
How to Apply
Qualified taxpayers must file an application with the Revenue District Office (RDO) that has jurisdiction over their registration. Upon approval and payment of the ₱5,000 fee, the RDO will issue a Certificate of Availment, official documentation that the covered case has been closed and the taxpayer’s record updated.
Steps to take now:
- Confirm you meet the gross sales threshold (≤₱3M) and liability cap (≤₱80,000 per taxable year)
- Identify which cases you need to cover, delinquent accounts, pending assessments, or stop-filer gaps
- File your application at your RDO before December 31, 2026
- Pay the ₱5,000 abatement fee upon approval
- Receive your Certificate of Availment
How This Connects to BIR’s Business Closure Reform
This program was issued alongside and explicitly complements, RMC No. 47-2026, the BIR’s earlier circular that streamlined and simplified the process for closing and cancelling a business registration, with tax clearances now issuable in as fast as three days for qualified cases.
Together, both issuances address the same problem: micro taxpayers who have effectively stopped operating but still carry unresolved BIR records. The abatement program handles the financial side; the simplified closure process handles the registration side.
Our Take: What This Means for Your Business
This program is genuinely useful for a specific, and large group of micro business owners: those who stopped filing, let their BIR records go dormant, or quietly wound down operations without ever formally clearing their obligations. For years, the cost and complexity of resolving those cases made it easier to simply ignore them. RR No. 4-2026 removes that excuse.
The ₱5,000 flat fee is a meaningful concession. For context, a single BIR deficiency assessment on an unfiled return can easily exceed that amount before surcharges and interest are added. The tradeoff here, pay a defined, fixed amount and receive a Certificate of Availment is a straightforward financial decision for most qualifying taxpayers.
If you have clients in the micro segment, this is worth surfacing in your next client touchpoint before the December deadline.
Frequently Asked Questions
Can I avail of this program even if I’ve already stopped operating my business?
Yes, the program explicitly covers taxpayers who have already ceased business operations, as long as their liabilities existed as of December 31, 2025 and they meet the gross sales and liability thresholds.
What happens after I pay the ₱5,000 abatement fee?
The Revenue District Office will issue a Certificate of Availment confirming that the covered case has been officially closed and your BIR record updated.
Does this program cover cases currently under dispute or pending appeal?
Yes, assessments that are currently being disputed are eligible, whether preliminary or final.
Resolve Your BIR Liabilities with UNA
Old BIR obligations don’t disappear on their own, they accumulate surcharges, attract audit exposure, and follow a business even after it stops operating. RR No. 4-2026 offers a clean, time-limited exit for qualifying micro taxpayers.
UNA Tax and Accounting Services helps micro businesses and founders navigate BIR abatement programs:
- Reviewing your BIR records to confirm eligibility under the gross sales and liability thresholds
- Preparing and filing your abatement application with the correct RDO
- Coordinating your Certificate of Availment and updating your compliance records
- Pairing abatement with a formal business closure under RMC No. 47-2026 where applicable
Book a Free BIR Compliance Review with UNA →
Not ready for a full consultation? Subscribe to get updates like this every week.
Subscribe to UNA’s Weekly Compliance Digest →


