Estimating your sales and expenses to hit a filing deadline feels harmless. It isn’t.
The moment your declared figures stop matching what your suppliers, customers, and withholding agents have already reported to BIR, you are no longer just behind on bookkeeping; you are a candidate for a Letter of Authority. The assessment that follows rarely stops at the deficiency tax. Surcharge, interest, and compromise penalties stack on top of it.
This is how businesses that assumed they were “compliant enough” end up with a six-figure BIR bill for numbers nobody ever verified. Here is why estimated bookkeeping gets flagged, and how to clean it up before an audit does it for you.
Quick Answer: Why does BIR flag “estimated” sales and expenses?
BIR flags estimated entries because they rarely match the third-party data BIR already holds buyer and supplier declarations, withholding tax certificates, and bank records, and any mismatch is enough to put your file under review.
- Estimated sales often don’t match what your customers report as purchases
- Estimated expenses often don’t match what your suppliers report as sales, leaving a visible gap on both sides
- Round, repeating, or suspiciously even figures stand out against the irregular pattern of real transactions
- Estimated figures rarely reconcile cleanly with bank deposits, withdrawals, or payroll records
- Monthly totals that don’t roll up to annual totals signal entries adjusted after the fact
- Much of BIR’s matching is system-driven, so mismatches surface long before anyone manually opens your file
What Is “Estimated” Bookkeeping?
Estimated bookkeeping is recording sales or expense figures from rough approximations instead of actual invoices, receipts, or source documents; usually to get a return filed before a deadline.
- Most common during catch-up accounting, when months of unrecorded transactions pile up before a deadline
- Often used when receipts are missing, disorganized, or were never collected in the first place
- Treated by BIR as a red flag rather than a reasonable shortcut, because it cannot be matched against verifiable third-party data
- Different from documented cost allocations or rounding conventions, which are consistent and traceable
How BIR Catches Estimated Entries
BIR does not need to audit every business to spot a mismatch. Its Reconciliation of Listing for Enforcement (RELIEF) system compares the Summary Lists of Sales and Purchases that VAT-registered taxpayers file each quarter against the lists filed by everyone they transacted with. Withholding tax alphalists and Certificates of Creditable Tax Withheld at Source (BIR Form 2307) add a second layer of matching.
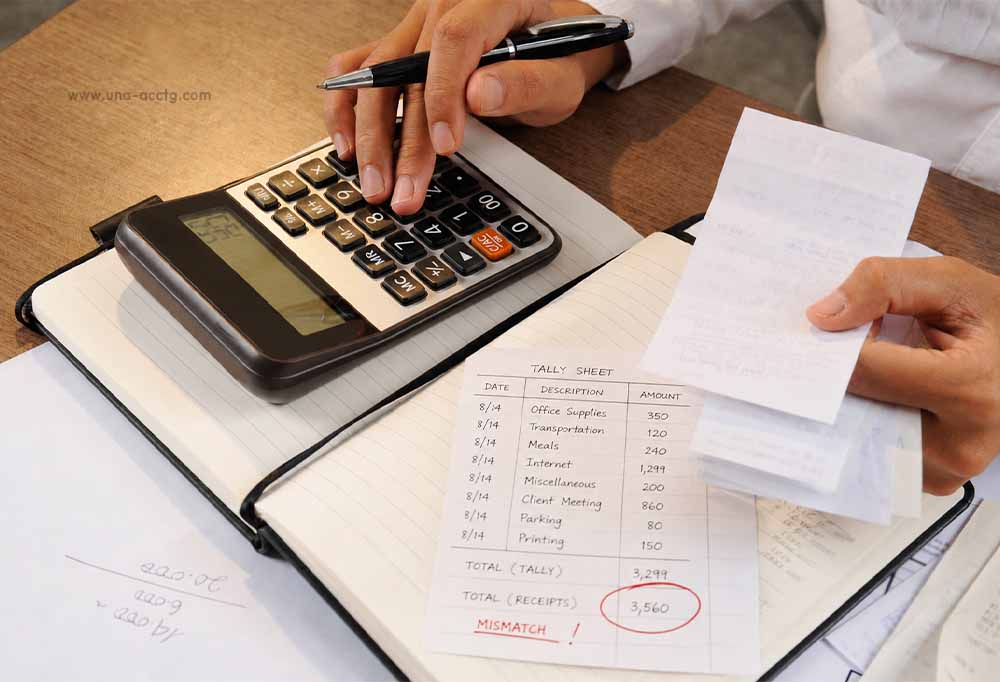
If your supplier declares a ₱2 million sale to you but your books show ₱1.2 million in estimated purchases, that ₱800,000 gap sits in BIR’s system until an assessment officer picks it up.
Fix: Reconcile your recorded sales and purchases against your 2307s and your counterparties’ invoices; not against a rough recollection of the period.
Common Ways Estimating Creeps Into Your Books
- Sales reconstructed from memory or bank deposits after receipts or POS records go missing
- Purchases estimated as a percentage of revenue instead of pulled from actual supplier invoices
- Inventory values estimated instead of physically counted at period-end
- Expenses “smoothed” evenly across months to avoid explaining an irregular pattern
Fix: Any month with incomplete source documents should be flagged and corrected within that same accounting period; not carried forward and guessed at during the next filing deadline.
What Happens When BIR Finds a Mismatch
A discrepancy does not jump straight to a bill. The process runs in stages, and each stage carries its own deadline:
- Letter of Authority (LOA) – BIR’s formal authority to examine your books
- Notice of Discrepancy (NOD) – issued under Revenue Regulations No. 22-2020; you have 30 days from receipt to present documents and explanations
- Preliminary Assessment Notice (PAN) – 15 days to reply in writing
- Formal Letter of Demand / Final Assessment Notice (FLD/FAN) – 30 non-extendible days to protest, or the assessment becomes final and executory
On top of the deficiency tax, Sections 248 and 249 of the Tax Code impose a 25% surcharge (50% where there is willful neglect or a false or fraudulent return), 12% annual interest on the unpaid tax, and a compromise penalty based on the schedule under Revenue Memorandum Order No. 7-2015.
One nuance worth knowing
Under the Ease of Paying Taxes Act (Republic Act No. 11976) and Revenue Regulations No. 6-2024, micro and small taxpayers pay a reduced 10% surcharge and 6% interest. Revenue Regulations No. 8-2024 sets the brackets by gross sales: micro is below ₱3 million and small is ₱3 million to under ₱20 million. At ₱20 million and above you are a medium taxpayer, and the full 25% and 12% rates apply. Crossing that threshold quietly doubles your penalty exposure on the same mistake.
The Real Cost of “Just Estimating It”
An assessment costs more than the deficiency amount. It costs the weeks spent responding to notices, the accountant hours spent reconstructing years-old records under pressure, and the cash-flow hit of settling a bill you never budgeted for.
Businesses that estimate to get through a deadline are usually the same ones that pay more, later, to fix what estimating created.
Fix: If you cannot fully document a period by the deadline, file on time using the figures you can actually support, then amend once the records are complete. A return may be amended within three years of filing; but only while BIR has not yet served a notice of audit for that period. Waiting closes that door.
Quick Answer: How do businesses fix estimated or incomplete books?
Businesses fix estimated books through a structured cleanup; rebuilding transactions from actual source documents, reconciling against the data BIR already holds, and correcting past filings before BIR does it for them.
- Pull actual invoices, official receipts, and bank statements for every affected period
- Reconcile recorded sales against the 2307s issued to you by your customers
- Reconcile recorded purchases against supplier invoices and the 2307s you issued
- File amended returns where the discrepancy is material, while you still can
- Set up a consistent chart of accounts and a monthly close process going forward
- Get a tax health check done proactively before a notice arrives, not after
Bookkeeping Cleanup Checklist: From Estimated to Accurate
Monthly
- Reconcile bank statements against recorded sales and expenses
- Match every recorded sale to an invoice or official receipt
- Match every recorded expense to a supplier invoice or receipt
Quarterly
- Cross-check the Quarterly VAT Return (BIR Form 2550Q) against your sales and purchase ledgers
- Confirm your Summary Lists of Sales and Purchases agree with what you filed on the 2550Q
- Reconcile withholding tax remittances against expenses subject to expanded withholding tax
Ongoing
- Keep source documents; digital or physical for every transaction as it happens
- Resolve any period with missing documents within that same month, not at year-end
The Bottom Line
Estimating gets a return filed on time. It does not make you compliant; it just delays the moment BIR notices the gap.
The businesses that avoid deficiency assessments are not the ones that estimate carefully. They are the ones that tie every figure to a real document before it is filed. If your books have relied on estimates to catch up, cleaning them up is the first thing proper accounting services in the Philippines should be doing for you, and it should happen before BIR’s cross-matching gets there first.
Book a Free Compliance Review with UNA
Estimated entries are a compliance gap waiting to be found, and BIR’s cross-matching will find it eventually. UNA Tax and Accounting Services helps Philippine businesses close these gaps before they turn into an assessment:
- A full reconciliation of your recorded sales and expenses against actual source documents
- Cross-matching against BIR’s third-party data before BIR does it for you
- A clear action plan to correct estimated entries and prevent them from recurring