
VAT compliance is one of the most closely audited areas in Philippine tax enforcement — and one of the most frequently mismanaged. Most businesses don’t discover their VAT exposure until they receive a Letter of Authority or a Preliminary Assessment Notice from the BIR. By then, what started as a recordkeeping gap has compounded into penalties, deficiency assessments, and the cost and disruption of a full audit.
The good news: most VAT audit triggers are preventable. This guide covers the most common errors Philippine businesses make, why they attract BIR scrutiny, and what you can do to stay ahead of them.
Quick Answer: What Triggers VAT Audits in the Philippines?
VAT audits are triggered by inconsistencies in tax filings, undocumented input VAT claims, and discrepancies that surface through the BIR’s data-matching systems.
Common audit triggers include:
- Mismatch between reported gross sales and VAT declarations
- Overclaimed or insufficiently documented input VAT
- Missing, invalid, or non-BIR-registered invoices
- Late or incorrectly computed VAT return filings
- Discrepancies identified through the BIR’s third-party data-matching tools (e.g., Summary List of Sales and Purchases / SLSP, alphalist data, withholding certificates)
What Is VAT Compliance in the Philippines?
VAT compliance means correctly computing, recording, reporting, and remitting value-added tax in accordance with the National Internal Revenue Code (NIRC), as amended by the TRAIN Law (RA 10963), and applicable BIR revenue regulations.
For VAT-registered businesses in the Philippines, this means:
- Charging and collecting 12% output VAT on all taxable sales of goods and services
- Claiming input VAT credits only on purchases properly supported by valid VAT invoices from VAT-registered suppliers
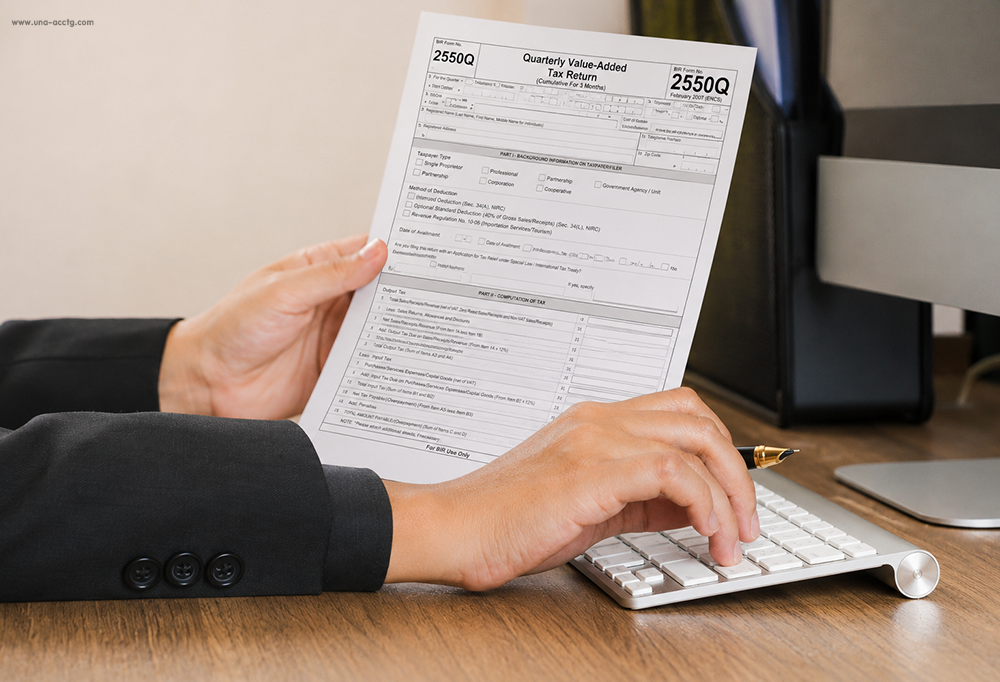
- Filing quarterly VAT returns (BIR Form 2550Q) within 25 days after the close of each taxable quarter — the monthly return (BIR Form 2550M) was abolished for mandatory filing effective January 1, 2023, under Section 37 of the TRAIN Law as implemented by RR 13-2018 and clarified under RMC 5-2023
- Maintaining complete books of accounts and all supporting documents throughout the applicable retention period
When any of these break down — even partially — compliance gaps open, and the BIR’s audit systems are increasingly effective at finding them.
Why VAT Errors Go Undetected Until It’s Too Late
Many business owners assume that filing on time is enough. It isn’t. Filing on time only protects you from late-filing penalties — it doesn’t protect you from a deficiency assessment triggered by incorrect reporting.
The most common reasons VAT errors go uncorrected:
- No monthly reconciliation between accounting records and the VAT return
- Bookkeeping maintained by someone without formal tax training
- Input VAT invoices booked without validating supplier registration
- VAT returns prepared under deadline pressure, without an internal review step
- Heavy reliance on manual spreadsheets with no validation controls
- By the time BIR flags an inconsistency — whether through its SLSP data, alphalist cross-matching, or an eAudit — the opportunity for voluntary correction has usually passed.
5 VAT Compliance Errors That Most Commonly Trigger BIR Audits
1. Mismatch Between Gross Sales and VAT Declarations
This is the single most common VAT audit trigger — and almost always preventable.
The BIR cross-references your VAT returns against your income tax returns, your customers’ withholding tax certificates, and the alphalist and SLSP data submitted by both your business and your counterparts. When your declared sales don’t reconcile across these data points, BIR takes notice.
Common causes:
- Transactions recorded in accounting in one period but reported in the VAT return for a different period
- Sales reflected in the books but inadvertently omitted from the quarterly return
- Discrepancies introduced by manual spreadsheet errors during VAT computation
- Disconnected accounting and tax preparation workflows with no reconciliation step
Fix: Perform a three-way monthly reconciliation — sales books, VAT return, and alphalist/SLSP submissions — before filing each quarter. Flag and resolve discrepancies before they accumulate.
2. Incorrect or Excess Input VAT Claims
Claiming input VAT you’re not legally entitled to is one of the fastest ways to draw BIR scrutiny — and it can escalate into a tax fraud investigation if ghost receipts are involved.
Under Section 110 of the NIRC, input VAT is creditable only when it is: (a) supported by a valid VAT invoice from a VAT-registered supplier, (b) incurred in the course of trade or business, and (c) not otherwise disallowed by law or regulation. Under RR 7-2024 (which implements the invoicing provisions of the EOPT Act, RA 11976, effective January 2024), VAT invoices are now the primary document evidencing both the seller’s output liability and the buyer’s input VAT claims.
Common mistakes:
- Claiming VAT credits from suppliers who are not VAT-registered with the BIR
- Including personal or non-business expenses in the input VAT schedule
- Booking invoices from suppliers appearing on BIR’s list of flagged or invalid receipts
- Failing to validate supplier TINs and VAT registration before recording the transaction
Fix: Validate every supplier’s VAT registration status through the BIR’s TIN verification facility before booking any input VAT. Review your input VAT schedule monthly — not just at the end of the quarter.
3. Missing or Invalid Supporting Documents
Quick Answer: Can a business claim input VAT without a valid invoice? No. Under RR 7-2024 (implementing Section 113 of the NIRC as amended by the EOPT Act), VAT invoices are the required supporting document for input VAT claims. Entries without proper documentation are disallowed and expose the business to assessment.
What counts as a valid VAT invoice under current rules:
- Issued by a BIR-registered, VAT-registered supplier
- Contains all required fields: seller’s name, address, TIN with branch code; buyer’s name, address, and TIN (required for transactions of ₱1,000 or more to a VAT-registered buyer); date; description and quantity; total amount; and VAT shown as a separate line item
- Marked “VAT-exempt sale” or “zero-rated sale” where applicable
Fix: Implement a document validation checklist for all purchases. No invoice = no booking for input VAT purposes. Assign a specific person to verify compliance before each quarterly filing.
4. Late or Incorrectly Computed VAT Filings
Late filing and computation errors both attract penalties — and unlike other mistakes, they’re difficult to argue once the due date has passed.
Mandatory quarterly VAT returns (BIR Form 2550Q) are due within 25 days following the close of each taxable quarter. Under the NIRC as amended by RA 11976 (EOPT Act, effective January 22, 2024), the following penalties apply to non-filing or underpayment:
- 25% surcharge on the tax due — reduced to 10% for micro and small taxpayers (gross sales below ₱20 million) for failure to file and pay, unless the failure is willful or involves a fraudulent return
- 12% annual interest on unpaid taxes — reduced to 6% per annum for micro and small taxpayers under the same conditions
- Compromise penalties based on the amount of tax involved
Important nuance: The reduced surcharge (10%) and interest rate (6%) under the EOPT Act apply only to micro taxpayers (below ₱3 million gross sales) and small taxpayers (₱3 million to ₱20 million gross sales). Medium and large taxpayers remain subject to the standard 25% surcharge and 12% interest.
Fix: Build the quarterly VAT return preparation into your accounting workflow, with an internal deadline at least three business days before the BIR due date. That buffer allows for review, correction, and on-time submission.
5. Weak Reconciliation Between Accounting Records and Tax Filings
The most systemic — and most expensive — VAT problem is a persistent disconnect between what’s in your books and what’s in your tax returns.
When accounting and tax preparation happen in silos, discrepancies accumulate quietly across quarters. By the time they’re noticed — or flagged by BIR — unwinding them is complex, costly, and sometimes impossible without professional help.
Common root causes:
- No assigned person responsible for the reconciliation process
- Month-end close rushed without a tax review step
- Reliance on manual spreadsheets with no cross-validation
- Returns submitted without a formal internal sign-off step
Fix: Treat quarterly VAT reconciliation as a mandatory step in your financial close process, not an optional review. It should happen before the return is filed — not after.
Quick Answer: How Do Businesses Avoid VAT Compliance Errors?
Businesses avoid VAT errors by building structured compliance systems, reconciling consistently, and validating supporting documents before every filing.
Key actions:
- Maintain up-to-date, accurate bookkeeping throughout the quarter — not just at filing time
- Perform a three-way reconciliation every quarter: sales books, VAT return, and alphalist/SLSP data
- Validate all input VAT invoices before booking — confirm supplier VAT registration status
- Conduct an internal review of every VAT return before submitting it
- Stay current on BIR issuances — VAT rules, invoicing requirements, and form versions change periodically
- Address discrepancies immediately; never defer resolution to the next quarter or year-end
A Practical VAT Compliance Workflow for Philippine Businesses
If your business doesn’t have a documented VAT process, this is a workable starting point.
Every month:
- Post all sales and purchase transactions accurately and on time
- Identify VAT-applicable transactions and confirm the correct rate or exemption
- Compute output VAT and reconcile against sales records
- Review input VAT schedule — validate invoices and flag any supplier concerns
- Reconcile books against prior VAT data and SLSP submissions
Every quarter:
- Prepare BIR Form 2550Q
- Perform a final three-way reconciliation before filing
- Review internally and file within 25 days of quarter-end
- File the Summary List of Sales, Purchases, and Importations (SLSP) if applicable
Ongoing:
- Maintain organized, complete files of all VAT invoices and supporting documents
- Monitor BIR announcements — especially updates to form versions, e-invoicing rules, and rate changes
- Flag and resolve exceptions immediately; do not accumulate open items
Common Challenges — and What They Actually Signal
| What businesses say | What it actually means |
| “We don’t have time to reconcile monthly” | Audit risk is compounding every quarter |
| “Our bookkeeper handles everything” | No review layer means errors go undetected |
| “We only act when BIR sends a notice” | BIR’s data-matching is already ahead of you |
| “We use spreadsheets” | Manual processes create the gaps that structured systems close |
Conclusion: Stay Compliant, Stay in Control
VAT errors don’t stay small. A missed reconciliation, an unsupported input VAT entry, or a filing with incorrect computations can turn into a deficiency assessment with 25% surcharge, 12% interest, and compromise penalties attached. The businesses that consistently avoid audits aren’t lucky — they’ve built the right processes and maintain them throughout the year.
If you’re not confident your VAT filings are accurate and your documentation is complete, the most important thing you can do right now is find out — before the BIR does.
Get a VAT Compliance Review with UNA
Unsure whether your VAT process is clean? Find out before BIR does.
VAT errors don’t announce themselves — they surface during audits, when correcting them is costly. UNA Tax and Accounting Services provides structured VAT compliance reviews for Philippine businesses: covering your quarterly filings, input VAT documentation, reconciliation process, and audit readiness.
UNA helps you:
- Identify VAT errors and documentation gaps before they become assessments
- Reconcile your books, VAT returns, and SLSP submissions
- Strengthen your internal controls and quarterly filing process
- Prepare your records if a BIR examination is already in progress
Don’t wait for a Letter of Authority to find out where your gaps are.


